
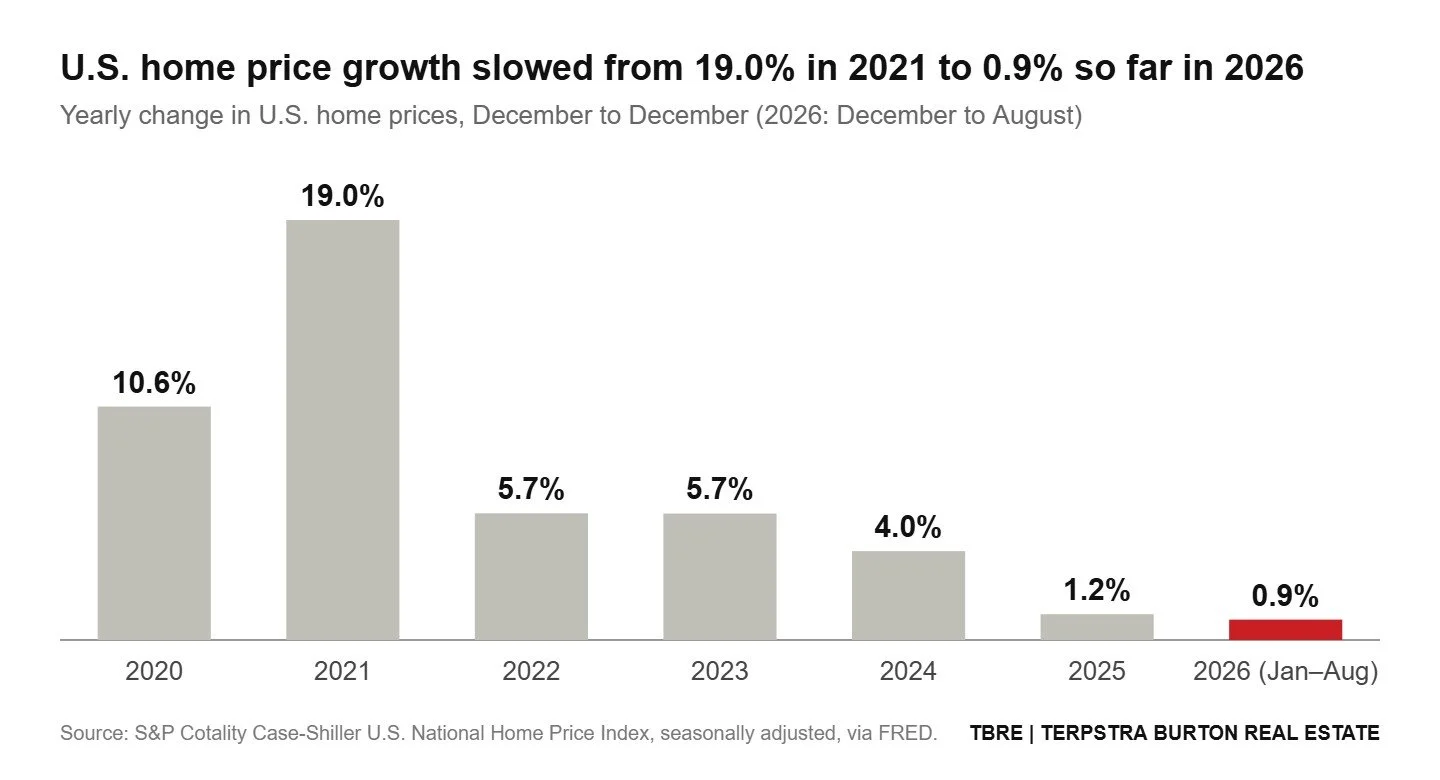
U.S. home prices have risen about 3.7% a year since the end of 2021, but just 0.9% in the first eight months of 2026. In Holland and Ottawa County, prices are about where they were a year ago!
Home price growth by year in the 2020s
U.S. home price growth has slowed every year since 2021, and through August, 2026 is running below 2025.
The 0.9% counts from December to August. Compared with August 2025, prices were up 2.1%, while inflation ran at 3.4%. That means home values fell in real terms for the 15th month in a row (S&P Dow Jones Indices). Has the market flipped from a Seller to a Buyer market? Let's look locally.
What prices are doing in Holland and Ottawa County
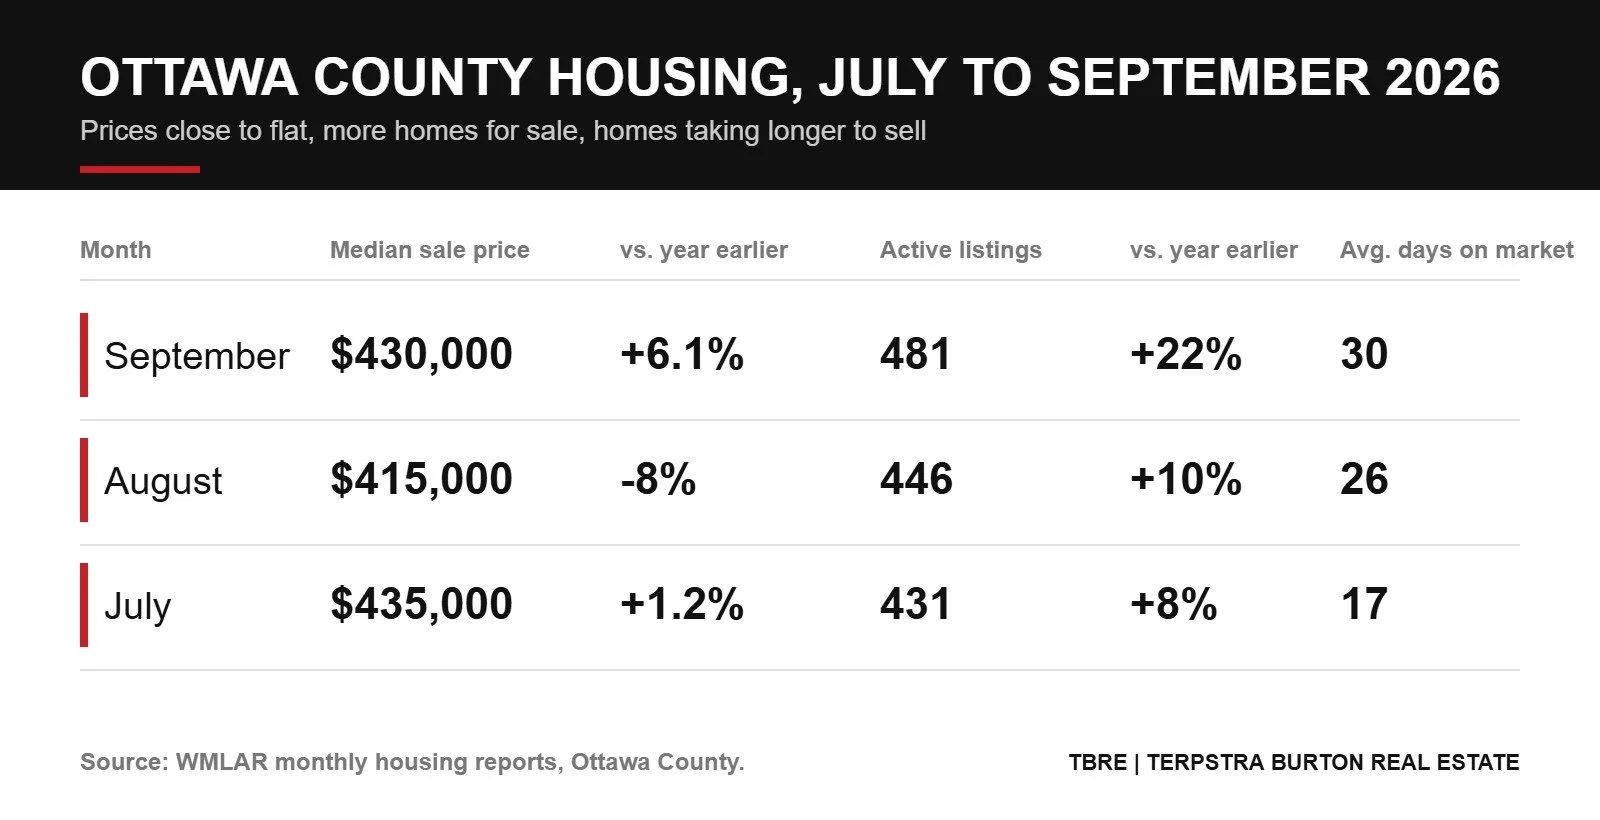
Ottawa County prices have been close to flat too, while the number of homes for sale keeps climbing.
September 2026: median sale price $430,000 (+6.1% vs. a year earlier), 481 active listings (+22% vs. a year earlier), and 30 average days on market.
August 2026: median sale price $415,000 (-8% vs. a year earlier), 446 active listings (+10% vs. a year earlier), and 26 average days on market.
July 2026: median sale price $435,000 (+1.2% vs. a year earlier), 431 active listings (+8% vs. a year earlier), and 17 average days on market.
Source: WMLAR housing reports for July, August, and September 2026, Ottawa County.
One month's median moves with whichever homes happened to sell that month, so we read the three months together. Prices are about where they were a year ago, buyers have more homes to choose from, and homes took 30 days to sell in September, up from 17 in July.
Why prices have stalled
Three things in the data are holding prices back: higher mortgage rates, more homes for sale, and fewer sales.
Higher mortgage rates. Freddie Mac's average 30-year fixed rate was 7.28% on October 1, 2026, up from 6.34% a year earlier (Trading Economics). The same price now costs more each month, which limits what buyers can offer.
More homes for sale. Ottawa County listings were up 8% to 22% from a year earlier in each month this summer (see above).
Fewer sales. 211 Ottawa County homes sold in September, down 24% from a year earlier (WMLAR).
Put together, buyers have more choices and less urgency. Sellers can't count on the market to raise their price for them, and buyers can't count on it to cover a problem they miss.
What you can do if you're selling
When prices aren't rising on their own, your house has to earn its price.
With more listings to compare, buyers walk past homes that look tired and pay more for the ones that feel like great value. Rising prices used to cover a scuffed wall or a dated kitchen. Now buyers notice them, and they count them against the price.
Fix what an inspector will flag. A roof near the end of its life, grading that slopes toward the house, or an old water heater can turn into a repair request or a lower offer. A walk-through before you list lets you decide what to fix, instead of the buyer's inspector deciding for you.
Make the inexpensive cosmetic updates. Light neutral paint, new light fixtures and cabinet hardware, refinished floors or new carpet, and a clean, trimmed yard change how every room photographs and shows.
Add the upgrades buyers pay for. New countertops, a home office, a built-in nook, a coffee bar, or wall sconces can add more value than they cost.
Price from recent sales, not old headlines. What sold nearby in the last few months tells us more than what prices did in 2021.
Major remodels and additions are a bigger decision, and they don't always pay back when you sell.
What you can do if you're buying
A flat market gives buyers time and choices, but it also means a house won't grow its way out of a problem you missed.
You have room to compare. With more homes on the market than a year ago, it's easier to tell a fair price from a hopeful one.
Inspect like it matters, because it does. When prices were climbing fast, rising value could cover a surprise roof or drainage repair. Today, a missed problem stays your cost. Look closely at the roof, the foundation, the windows, and the drainage on every showing.
Don't pass on a good house over dated finishes. Paint, fixtures, and flooring are inexpensive to change, and homes that look tired can sit longer, which can leave room to negotiate.
Start with the monthly payment. With rates above 7%, ask your lender to run your numbers before you tour.
For the full process, see our guide to buying a home in Holland, MI.
How we can help
Everyone looks brilliant when the market is going up 10% a year. Under slow conditions, adding value (before the sale or after the purchase) is our bread and butter. If you need help protecting your home's sale price, or getting to a fair price on your dream home, that's our specialty.
So, come talk to us!
We build plans that drive the most value for you.
Liz Burton (616) 218-6402 lizburton@homelakeshore.com
Sean Terpstra (616) 886-9839 sean@homelakeshore.com
Sources: FRED, S&P Cotality Case-Shiller U.S. National Home Price Index (seasonally adjusted), also charted by Ritholtz Wealth Management; S&P Dow Jones Indices, Case-Shiller release for August 2026; WMLAR, West Michigan Housing Market July 2026; August 2026; September 2026; Trading Economics, U.S. 30-year mortgage rate